
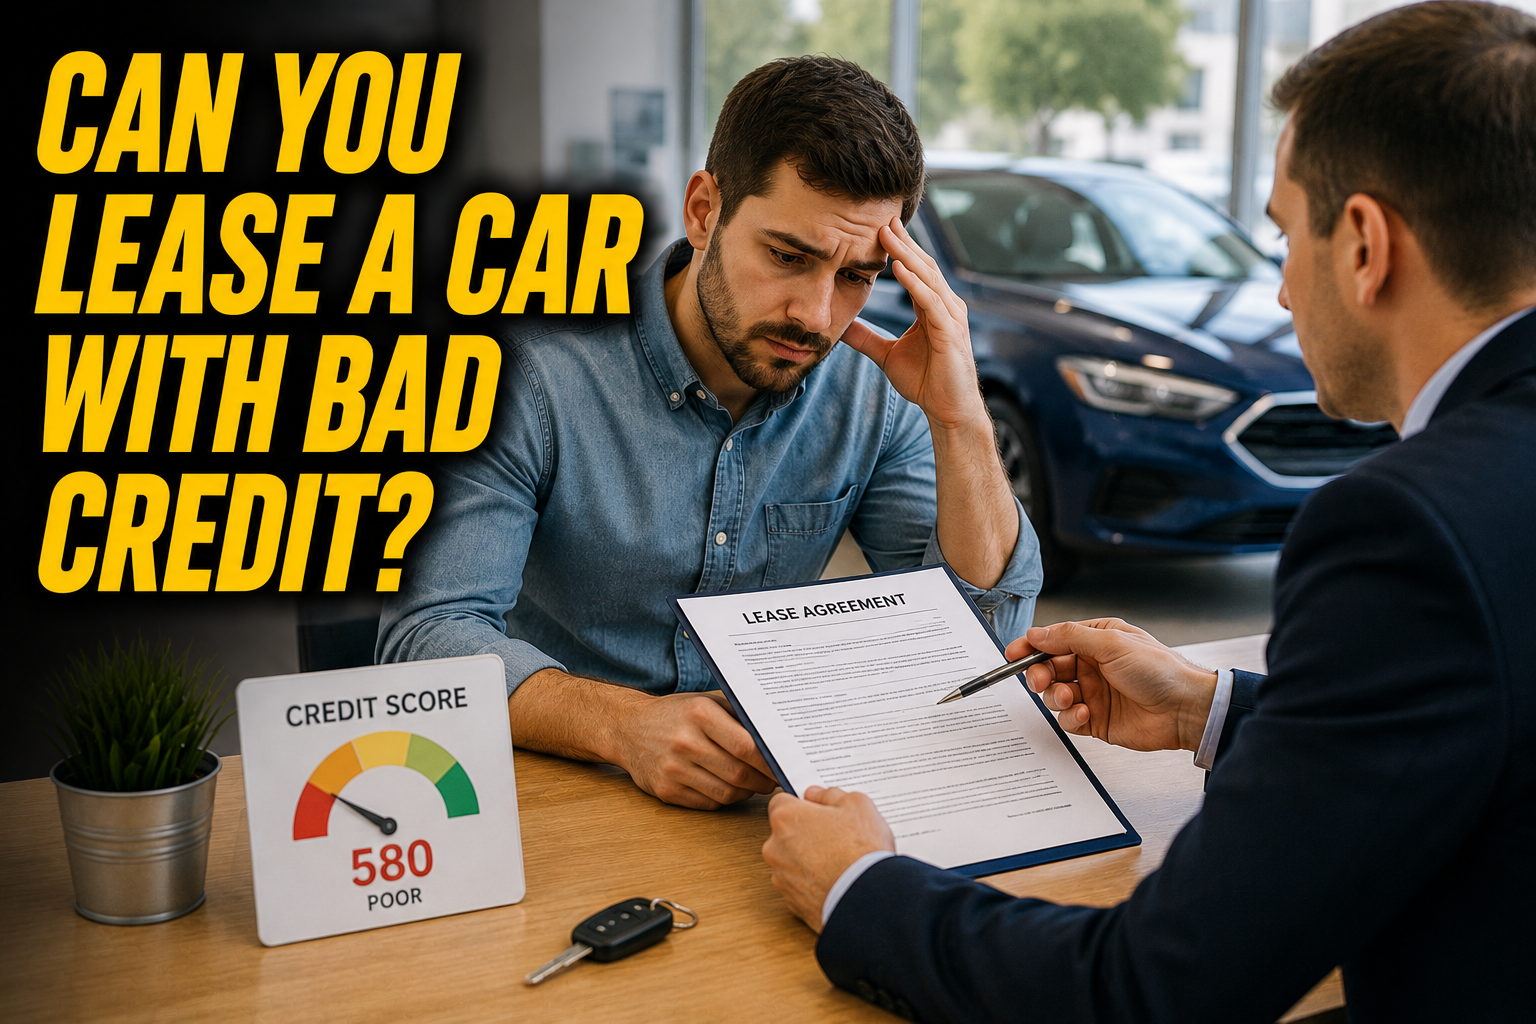
Sometimes, but leasing has a higher credit bar than borrowing to buy, and the gap surprises people. A score that gets you approved for a used car loan may not get you approved for a lease at all.
- What score you actually need?
- Why leasing is stricter than a loan?
- What poor credit actually costs?
- What improves your odds?
- The risks that hit harder when money is tight
- Practices to watch for
- Shopping without damaging your score further
- Alternatives worth pricing
- If you have a few months
- Conclusion
- Frequently asked questions
- Related Articles
There is no legal minimum. Every lender sets its own tiers. In practice most mainstream captive finance companies start looking at leases around the low 600s, the advertised deals are reserved for roughly 700 and up, and luxury brands rarely go below 650.
The more useful question is not whether you can, but what it costs when you do. That is where the numbers get uncomfortable, and it is worth seeing them before you sit down at a dealership.
What score you actually need?
Lenders group applicants into tiers and price each tier differently. The exact boundaries vary by company, but the shape is consistent.
| Rough score band | What to expect |
| 720 and above | Advertised lease specials, best money factors |
| 680 to 719 | Approval at most brands, slightly worse rate |
| 620 to 679 | Approval narrows, noticeably higher money factor, deposit may be required |
| Below 620 | Difficult at most captives, possible on some mainstream brands and models |
| Below 580 | Rare, and usually not on terms worth taking |
Two extra details are worth knowing. Lenders often use FICO Auto Scores rather than the general-purpose score you see on a free app, and those run on a 250 to 900 scale, so the number a dealer sees may not match the number you saw. And approval is never score alone: income, job stability, debt-to-income ratio, time at address, and whether you have paid off a car before all feed into it.
Why leasing is stricter than a loan?
This catches people out, because a lease feels like the cheaper commitment.
With a loan, the lender holds a lien on a car you own. If you stop paying, they repossess and sell it, and you carry any shortfall. Their exposure ends there.
With a lease, the lender owns the car for the whole term and is betting on what it will be worth when you hand it back. They are exposed to your payments, to the mileage you put on it, to the condition you return it in, and to the used market three years from now. More ways to lose money means a tighter credit filter.
That is also why lease approvals can hinge on the specific vehicle. A model with a strong residual forecast is a safer bet for the lender than one that is expected to fall hard.
What poor credit actually costs?
The money factor is where the damage shows up. Multiply a money factor by 2,400 and you get the approximate annual interest rate, which makes offers comparable.
A concrete illustration from the leasing world: on a common mid-size sedan, a lessee in a tier around 650 to 669 was calculated to pay roughly $58 a month more than someone at 720 or above, for exactly the same car on exactly the same terms. Over a 36-month lease that is about $2,088 in extra finance charges.
The other thing that changes is what you can lease at all. Advertised specials, the $299-a-month type of offer, are almost always subvented, meaning the manufacturer has bought the money factor down to make the payment look attractive. That subsidy is reserved for top-tier credit. Below it you get a standard bank rate, and the payment on the same car can be substantially higher than the one in the advertisement.
Anyone comparing an advertised lease payment against their own quote is comparing two different products.
What improves your odds?
Several levers genuinely move the needle, and they work in combination.
A co-signer with strong credit. The most effective single change. It also makes that person fully liable for every payment and every end-of-lease charge, so both people need to understand exactly what they are signing.
A bigger cap cost reduction. Putting money down reduces the lender’s exposure. It also means that if the car is stolen or written off early, that money is gone, which is why gap coverage matters more on a lease than almost anywhere else.
Multiple security deposits. Some lenders let you lower the money factor by leaving refundable deposits. Availability varies and it requires cash up front, but the deposits come back.
A cheaper car. Lower capitalized cost means lower risk and a smaller payment, and it widens the pool of lenders willing to write it.
Brand choice. Mainstream captives are generally more flexible than luxury ones. Programmes also change with incentive cycles, so a brand that says no this quarter may say yes next.
Applying where your history is. A previous on-time auto loan or lease with the same finance company is a strong signal in your favour.
The risks that hit harder when money is tight
Leasing carries obligations that are manageable on a comfortable budget and punishing on a stretched one. These deserve honest weight.
You cannot easily get out. With a loan you can sell the car and settle the balance, and if you have equity you walk away with something. A lease is a fixed contract, early termination charges are substantial, and there is no equity to draw on. A 36-month lease is a 36-month commitment in a way a loan is not.
Mileage overages accumulate. Allowances are typically 10,000 to 12,000 miles a year, with a per-mile charge above that. Long commutes turn into a bill you receive at the end, when you may be least able to absorb it.
Wear and tear charges land at the same moment. Kerbed wheels, seat damage, and paint scratches beyond the standard all get invoiced when you hand the car back.
And the whole lease obligation counts against your debt-to-income ratio, which affects anything else you apply for during the term.
None of this makes leasing wrong. It does mean the monthly payment is not the whole cost, and on a tight budget the end-of-lease charges are the part that hurts.
Practices to watch for
Consumers with weaker credit are targeted for specific tactics, and knowing the names helps.
The one to understand is the spot delivery, sometimes called yo-yo financing. You sign paperwork, drive the car home, and days or weeks later the dealer calls to say the financing did not go through and you need to come back and sign again at worse terms. Consumer advocacy organisations have documented the practice extensively, and the Center for Responsible Lending’s summary of auto financing practices covers it alongside dealer rate markups.
Two protections are simple. Do not leave with the car until the financing is confirmed as final rather than conditional, and ask to see written confirmation from the finance company. If you are asked to sign a conditional delivery agreement, read exactly what it lets the dealer do.
Add-ons are the other pressure point. Paint protection, fabric treatment, and similar products are frequently presented as required for approval. They are not, and each one increases the amount being financed.
You also have specific disclosure rights. Under the federal Consumer Leasing Act, a lessor must give you the costs and terms in a standard written format before you sign. The Federal Reserve’s consumer guide to vehicle leasing explains what those disclosures cover and how to read them.
Shopping without damaging your score further
There is a way to compare offers that does not cost you points, and it matters most when you have none to spare.
Credit scoring models treat multiple auto finance enquiries made close together as a single event, on the reasoning that you are shopping for one car rather than opening several accounts. The window is commonly somewhere between 14 and 45 days depending on which scoring model is used.
The practical version: do all your applications inside a fortnight. Applying at one dealer in January, another in March, and a third in May counts as three separate hits.
It also helps to arrive with financing already arranged. A pre-approval from a bank or credit union gives you a rate to measure the dealer’s offer against, and it removes the pressure to accept whatever is put in front of you at nine in the evening.
Ask for the money factor and the residual as numbers, not just the monthly payment. A dealer who will not give you those is telling you something.
Alternatives worth pricing
Get quotes on more than one structure before deciding, because with weaker credit the ranking often flips.
A used car loan on a modest, reliable vehicle usually costs more per month than a lease but leaves you owning an asset, and it builds payment history that improves your score.
A credit union is worth a call. They frequently approve applicants that captive lenders decline, and their rates for lower credit tiers tend to be better than dealer-arranged financing.
A lease takeover means assuming the remainder of someone else’s contract. It still requires lender approval, but the shorter remaining term is a smaller commitment.
Buying an inexpensive older car outright, if you can, removes the credit question entirely and buys you time to rebuild.
If you have a few months
Waiting is genuinely worth considering, because tier boundaries are cliffs rather than slopes. Moving from 645 to 665 can change both the answer and the price.
Pull your credit reports and check them for errors, which are common and free to dispute. Bring any past-due accounts current, because payment history carries the most weight. Pay down revolving balances, since utilisation responds quickly. And avoid opening new accounts or letting several dealers run your credit across a long period.
Three to six months of that can move you a tier, and a tier is worth more than any negotiation at the dealership.
Conclusion
You can sometimes lease with weak credit, but leasing screens harder than borrowing, the advertised deals require top-tier scores, and a lower tier can cost around two thousand dollars in extra finance charges over a typical term.
A co-signer, a larger down payment, a cheaper car, and a mainstream brand all improve your odds. Weigh the end-of-lease charges and the difficulty of exiting early against a used car loan, and if a few months of credit repair is possible, that usually buys more than anything you can negotiate.
Frequently asked questions
What credit score do you need to lease a car?
There is no legal minimum. Most mainstream captive lenders start around the low 600s, the best money factors go to roughly 720 and above, and luxury brands rarely approve below 650. Income and debt-to-income matter alongside the score.
Is it easier to buy or lease with bad credit?
Buying is generally easier. A lender’s exposure on a loan ends with repossession, while on a lease they own the car and carry the residual risk, so lease approvals are screened more tightly.
Can a co-signer help me lease a car?
Yes, and it is usually the most effective option. The co-signer becomes fully responsible for payments and for end-of-lease charges, so both parties should understand the full obligation first
Will leasing a car improve my credit?
A lease reports like other credit accounts, so consistent on-time payments help. The whole lease obligation also counts toward your debt-to-income ratio while the term runs.
Why is my lease quote higher than the advertised deal?
Advertised lease specials are usually subvented, meaning the manufacturer buys the money factor down for top-tier credit. Below that tier you receive a standard rate, which raises the payment on the same car.
Related Articles
Can You Jump Start a Car in the Rain? Safety Guide
Can Car Oil Expire? Shelf Life and Storage Explained
Can a Car Battery Die While Driving?